The instrument's own words
page 1 · read by Gemma vision
207
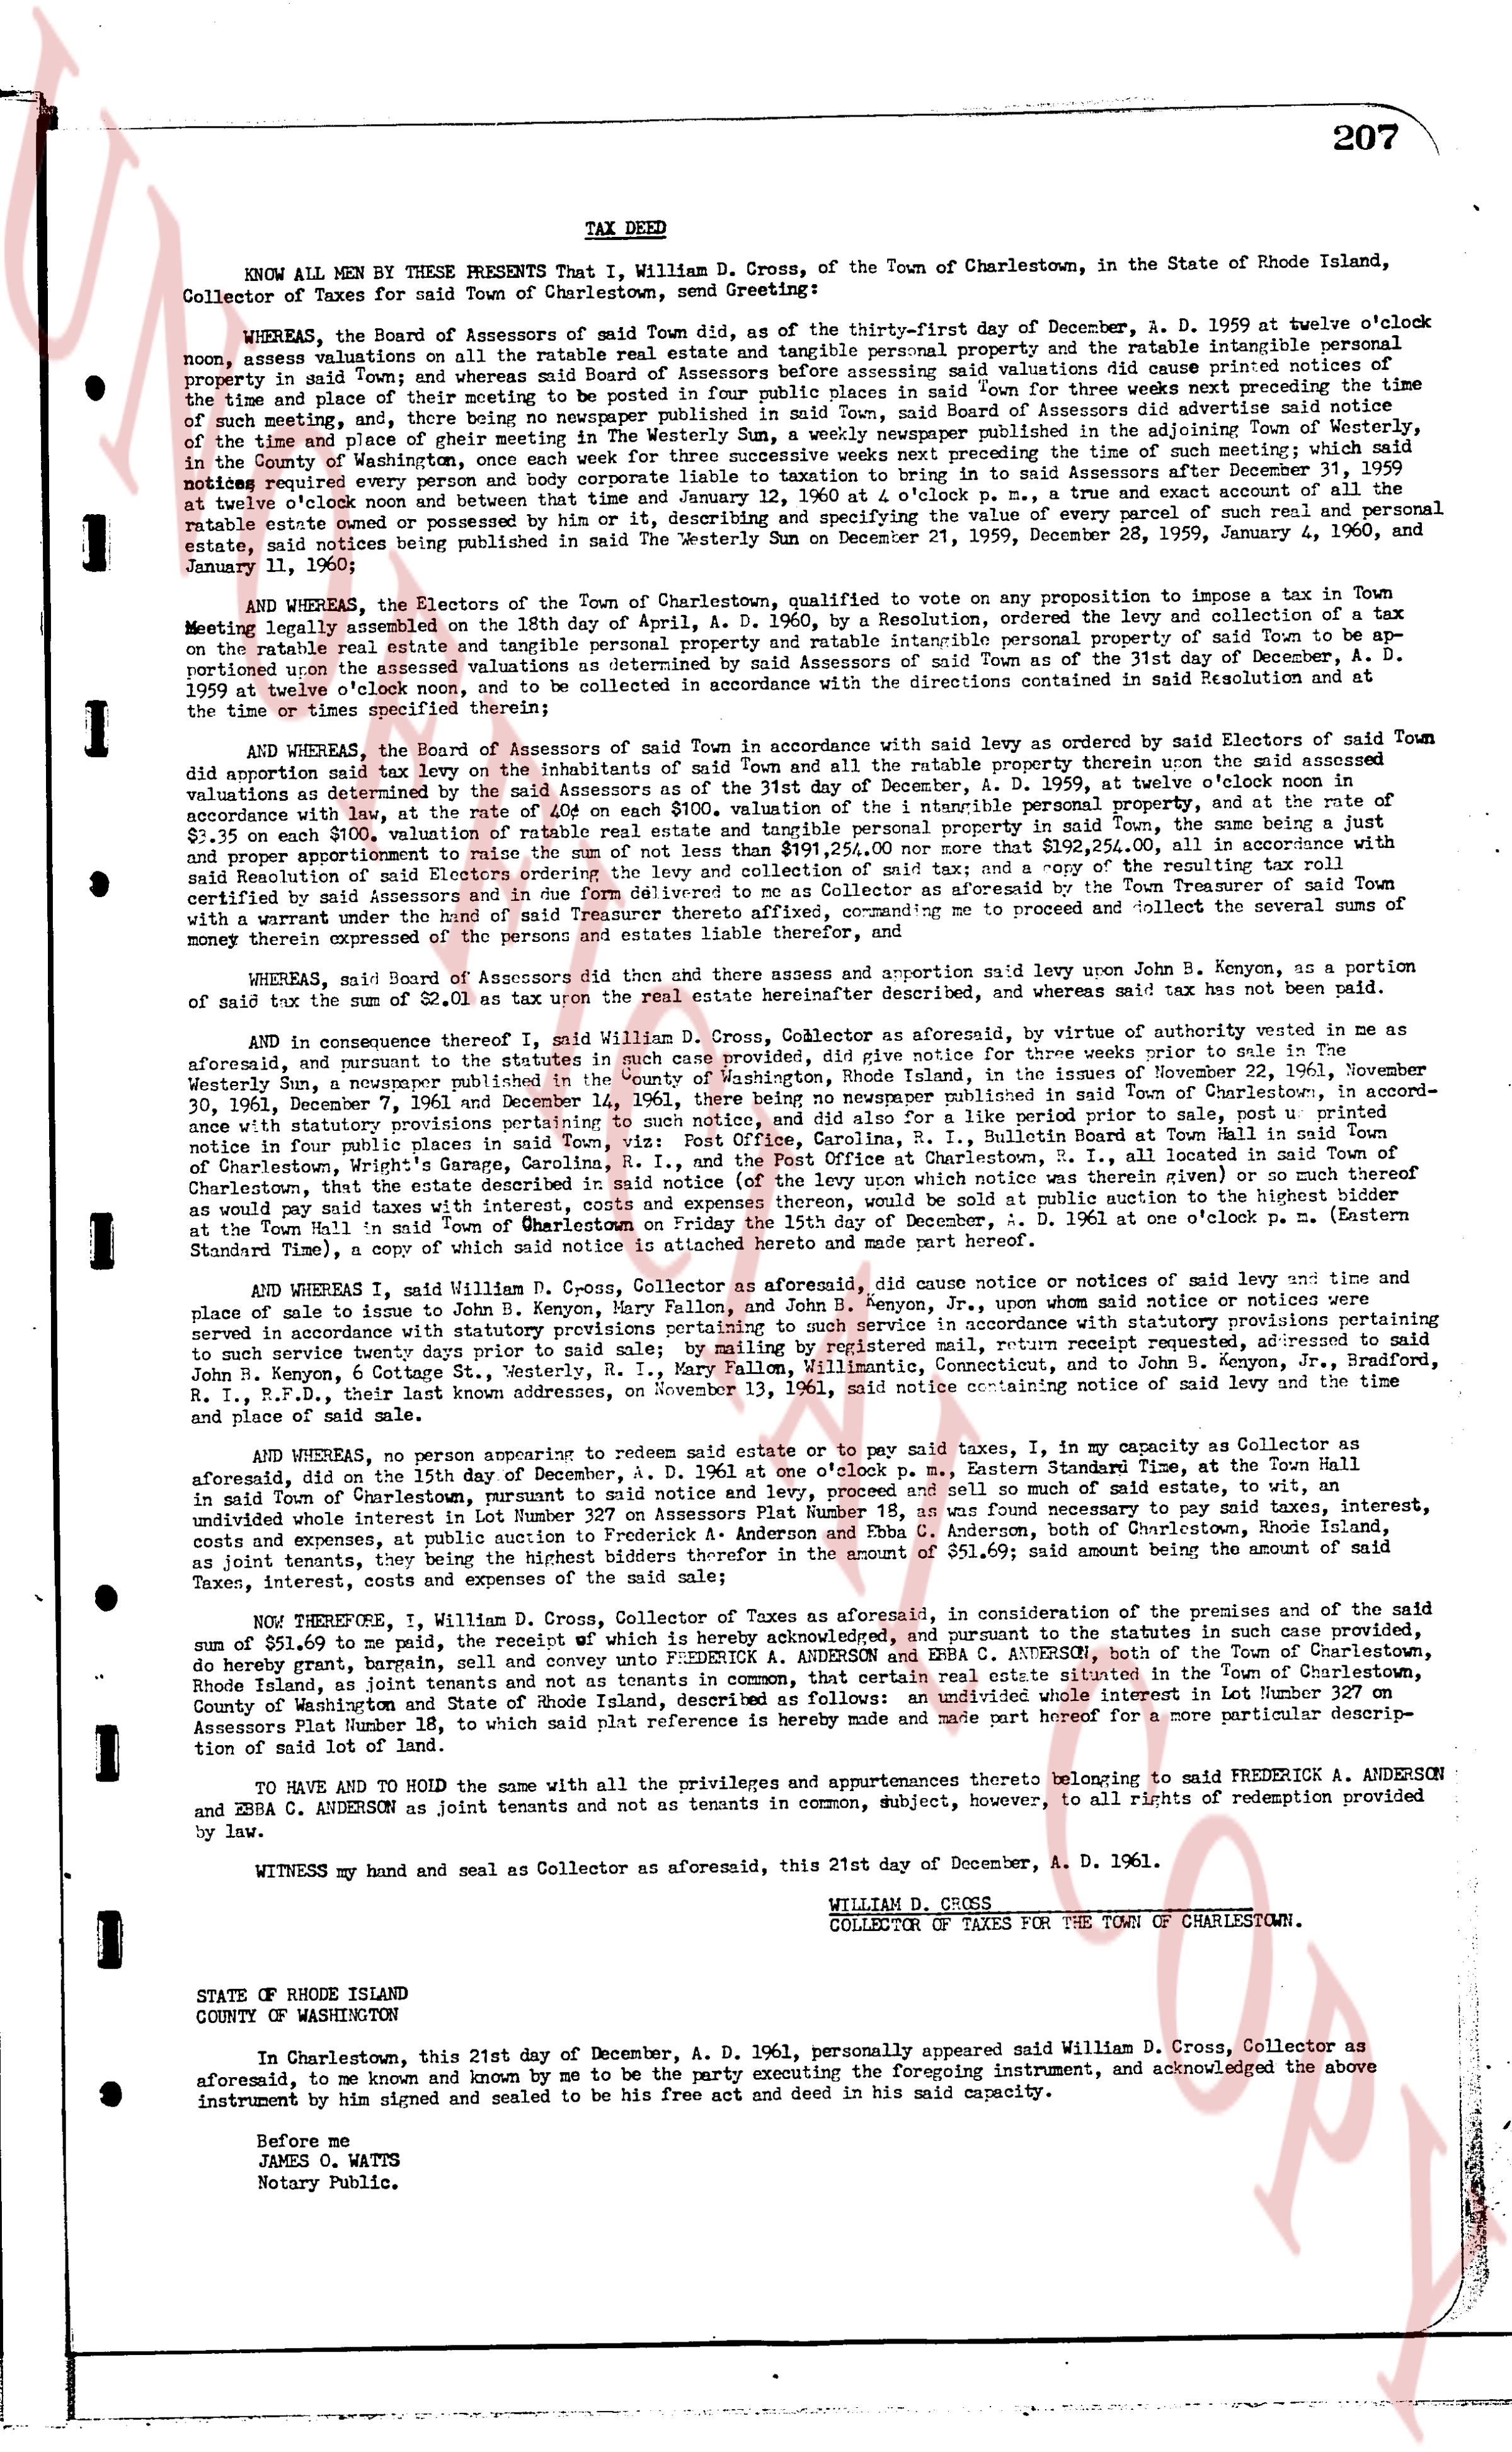
TAX DEED
KNOW ALL MEN BY THESE PRESENTS That I, William D. Cross, Collector of Taxes, of the Town of Charlestown, in the State of Rhode Island, Collector of Taxes for said Town of Charlestown, send Greeting:
WHEREAS, the Board of Assessors of said Town of Charlestown, on the thirty-first day of December, A. D. 1961 at twelve o'clock noon, assessed on all the real and taxable estate and tangible personal property and the ratable intangible personal property assessed in said Town; and whereas said Board of Assessors before assessing said valuations did cause printed notices of property and real valuations to be posted in said Town; and whereas said Board of Assessors did advertise said notice of the time and place of their meeting to be posted near the Town Hall; and whereas said notice of meeting was further published in said Town, said Board of Assessors did advertise said notice of the time and place of their meeting in the Westerly Sun, a weekly newspaper published in and circulated in the Town of Westerly, Washington County, Rhode Island, for three successive weeks preceding the time of such meeting; which said notice required every person and body corporate liable to taxation in bring to said Board of Assessors after 1st Tuesday next following the publication of said notice, a written statement of the value of every parcel of such real and ratable estate owned or possessed by him or his corporation, describing and specifying the value of every part of such real and personal property, and the same was due on or before the 1st Tuesday next following the publication of said notice, being Tuesday January 11, 1961.
AND WHEREAS, the Board of Assessors of said Town of Charlestown, qualified to vote on any proposition to impose a tax in Town meeting held on the 18th day of April, A. D. 1961, by a Resolution, entered and levied a collection of a tax on the ratable real estate and tangible personal property and ratable intangible personal property of said Town to be apportioned upon the assessed valuations as determined by the said Assessors of said Town to be the just and equitable valuation of the said real and personal property, and the same was levied in accordance with the directions contained in said Resolution and at the time of the sums specified therein;
AND WHEREAS, the Board of Assessors of said Town in accordance with said levy ordered by said Electors of said Town of said levy on the real and personal property of inhabitants of said Town and all the ratable property therein the said moon assessed valuations as determined by the said Assessors as of the 31st day of December, A. D. 1960 at the rate of $1.10 on each $100 valuation of the ratable intangible personal property, and at the rate of $3.25 on each $100 valuation of ratable real estate and tangible personal property in said Town, the some being a just and equitable valuation of the said real and personal property, and the same was levied in accordance with the directions contained in said Resolution of said Electors of ordering the levy and collection of said tax; and a copy of the resulting tax return certified by the Board of Assessors of said Town was filed with the Town Clerk of said Town, and the said Collector of Taxes, by the said Town Clerk, provided the said Collector of Taxes with a warrant under the seal of said treasurer after testifying, coming according to me and proceed to collect the several sums of money then expressed the persons of the taxpayers;
WHEREAS, said Town of Charlestown did then and there assess and assign levy upon said John B. Kenyon, a person by that station as well as upon the sum of $2.50 as the real tax the ratable estate hereinafter described, and whereas said tax has not been paid.
I and therefore conceive and think I, William D. Cross, Collector as aforesaid, by virtue of authority vested in me as aforesaid, and pursuant to the statutes in such made provided, and pursuant to the tax return filed with the Town Clerk of the Town of Charlestown, Rhode Island, in the issues of several papers published in three successive weeks prior to date, published in the Westerly Sun, a weekly newspaper published in and circulated in the Town of Westerly, Washington County, Rhode Island, in the issues of several papers published in three successive weeks prior to date, posted in four public places in said Town, viz. Post Office, Charlestown, R. I., Bulletin Board at Town Hall in said Town, and at the Town Hall in said Town, and whereas said notice of the time and place of said meeting was further published in the Town Clerk that the public is date described in said notice (if the levy of the town which one notice thrives) or as such therefore as to be known to all the inhabitants of said Town and all the ratable property therein the said moon assessed valuations at the Town Hall in said Town of Charlestown on the 15th day of December, A. D. 1961 at one o'clock p.m. (Eastern Standard Time), and a copy of which said notice was posted in the four public places aforesaid.
AND WHEREAS, I, William D. Cross, Collector as aforesaid, did cause notices of notice and levy of tax unit, when said notices or notice were sent, when said notices or notice were sent, by mail, return receipt requested, to the persons interested in said real estate and personal property to wit, namely to John B. Kenyon, Mary Fallon, and John B. Kenyon, Jr., upon whom said notices or notice pertaining to several in accordance with statutory provisions previously mentioned, and upon the persons interested in said real estate and personal property to wit, namely by registered mail, return receipt requested, addressed to said Mary Fallon, and John B. Kenyon, St. Westerly, R. I., Mary Fallon, William, Connecticut, and to said John B. Kenyon, Jr., St. Westerly, R. I., and whereas said notices or notice were sent, and whereas said notices or notice were sent, to said John B. Kenyon, St. Westerly, R. I., Mary Fallon, William, Connecticut, and to said John B. Kenyon, Jr., St. Westerly, R. I., and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said notices or notice were sent, and whereas said
page 2 · read by Gemma vision
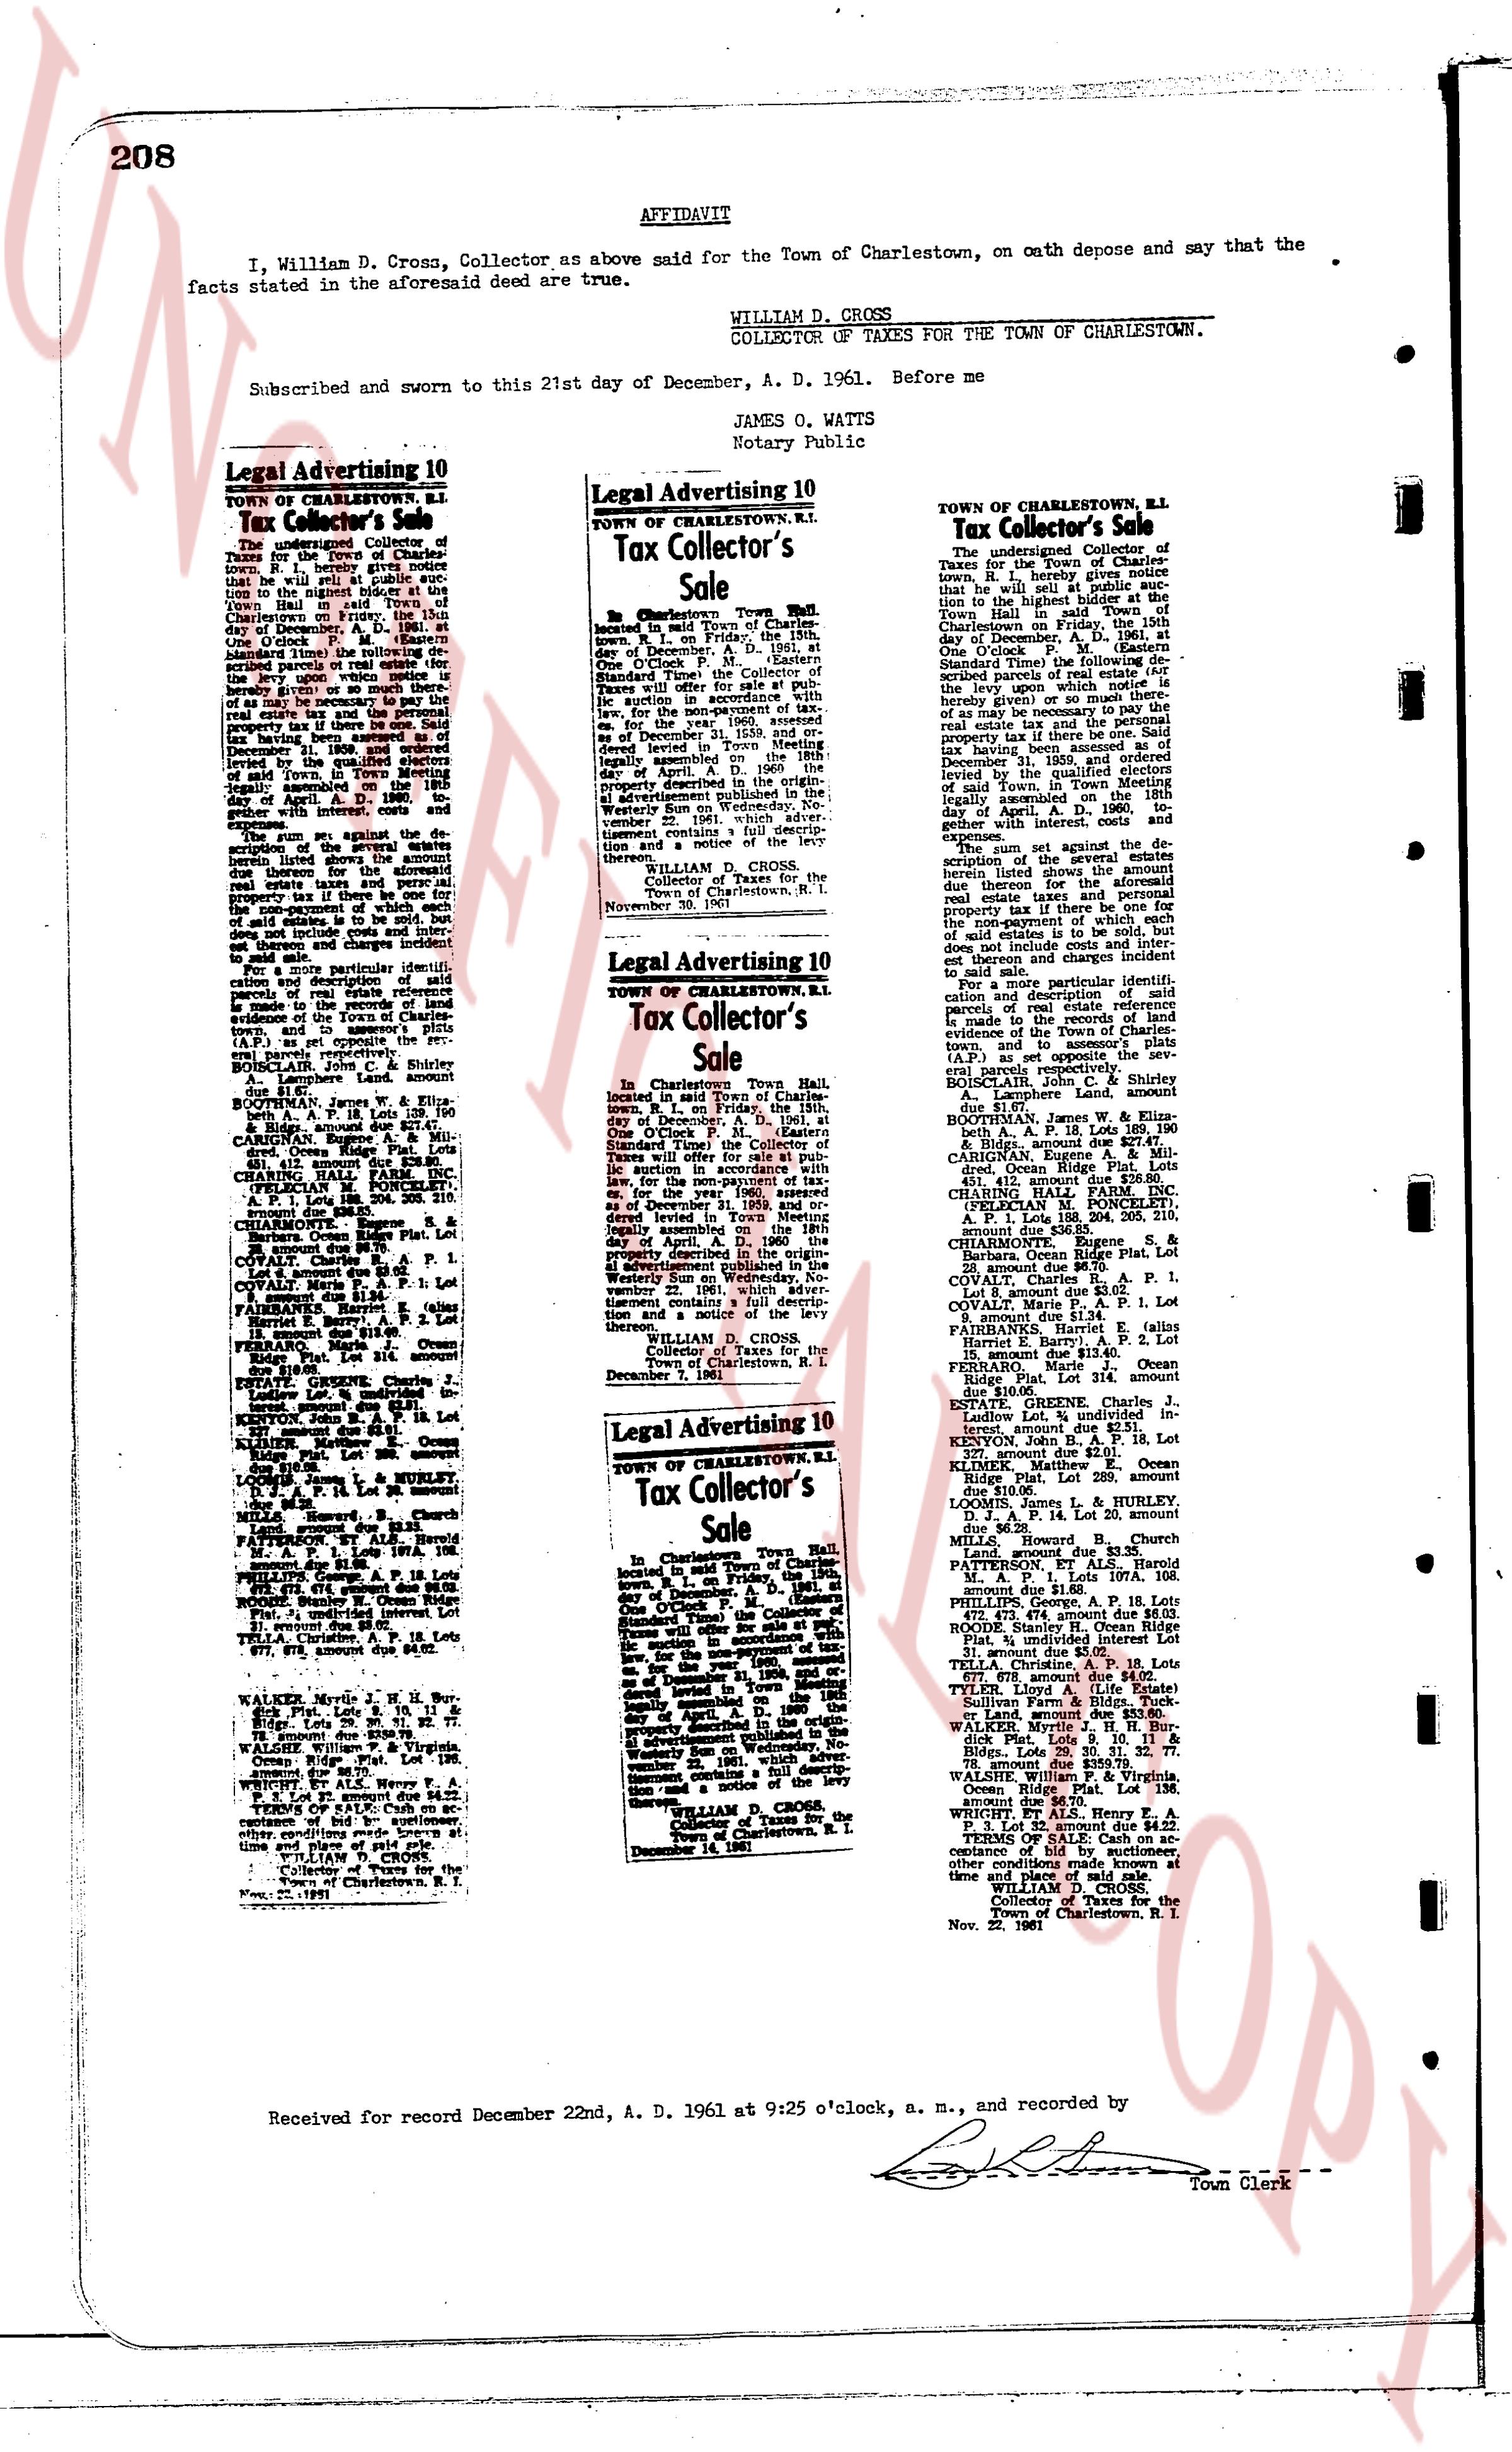
AFFIDAVIT
I, William D. Cross, Collector as above said for the Town of Charlestown, on oath depose and say that the facts stated in the aforesaid deed are true.
WILLIAM D. CROSS
COLLECTOR OF TAXES FOR THE TOWN OF CHARLESTOWN.
Subscribed and sworn to this 21st day of December, A. D. 1961. Before me
JAMES O. WATTS
Notary Public
----
Legal Advertising 10
TOWN OF CHARLESTOWN, R.I.
Tax Collector's Sale
Notice is hereby given that by virtue of a request made by the Collector of Taxes of the Town of Charlestown, R. I. to the said Town, and in accordance with the laws of the State of Rhode Island, the following described real estate situated in the Town of Charlestown, R. I., will be sold at public auction to the highest bidder on the 24th day of April, A. D. 1962, at 10 o'clock a.m., at the Town Hall, Charlestown, R. I., or at some other convenient place known to the parties interested, for the payment of taxes due and unpaid upon the same, together with interest, costs, and charges incidental thereto, and for the payment of the request money for the sale of the premises, provided that if the tax collector shall have received the amount of all taxes due and unpaid upon the premises before the time of sale, he shall cancel the sale.
The real estate to be sold is the following:
A certain plot of land located in the Town of Charlestown, R. I., being part of a larger tract of land formerly owned by John Kenyon, and now owned by various persons, consisting of approximately one acre, more or less, bounded on the North by land of Mary Fallon, on the East by land of John B. Kenyon, on the South by land of Frederick A. Anderson, and on the West by land of Ebba C. Anderson.
The property is further described as Lot No. 12 in Plat Book 38, Page 207, of the Land Evidence Records of the Town of Charlestown, R. I.
The terms of sale are cash in hand.
The properties listed below are also subject to the same conditions of sale:
BOUTELL, Wayne J. & Shirley Boutell, husband and wife, Plot Lot 124, amount due $12.50
CARBONE, Joseph P., Plot Lot 125, amount due $15.00
CARRION, Jose & Maria Carrion, husband and wife, Plot Lot 126, amount due $18.00
CHARLOTTEN, Robert, Plot Lot 127, amount due $12.00
COVALLY, Charles A. Jr., Plot Lot 128, amount due $14.00
DYLAN, James, Plot Lot 129, amount due $16.00
FAIRBANK, Sarah E., Plot Lot 130, amount due $11.00
FRENCH, George, Plot Lot 131, amount due $13.00
ESTATE, George Charles J., Plot Lot 132, amount due $17.00
KENTON, John B. Jr., Plot Lot 133, amount due $14.00
MURPHY, Patrick F., Plot Lot 134, amount due $15.00
RUELL, Philip A., Plot Lot 135, amount due $12.00
SULLIVAN, Thomas, Plot Lot 136, amount due $16.00
PATTERSON, G. H. A., Plot Lot 137, amount due $14.00
PHILIPS, George A. P., Lot 138, amount due $13.00
PENNEL, Albert L., Plot Lot 139, amount due $15.00
PRICE, unidentified heir, Lot 140, amount due $12.00
WALKER, Mary J. W., Plot Lot 141, amount due $14.00
WALTER, Henry S., Plot Lot 142, amount due $16.00
WOODS, Arthur, Plot Lot 143, amount due $13.00
TERMS OF SALE: Cash on demand.
WILLIAM D. CROSS
Collector of Taxes, Town of Charlestown, R. I.
Dec. 15, 1961
Legal Advertising 10
TOWN OF CHARLESTOWN, R.I.
Tax Collector's Sale
In Charlestown, Town Hall, notice is hereby given that by virtue of a request made by the Collector of Taxes of the Town of Charlestown, R. I. to the said Town, and in accordance with the laws of the State of Rhode Island, the following described real estate situated in the Town of Charlestown, R. I., will be sold at public auction to the highest bidder on the 14th day of February, A. D. 1962, at 10 o'clock a.m., at the Town Hall, Charlestown, R. I., or at some other convenient place known to the parties interested, for the payment of taxes due and unpaid upon the same, together with interest, costs, and charges incidental thereto, and for the payment of the request money for the sale of the premises, provided that if the tax collector shall have received the amount of all taxes due and unpaid upon the premises before the time of sale, he shall cancel the sale.
The real estate to be sold is the following:
A certain plot of land located in the Town of Charlestown, R. I., being part of a larger tract of land formerly owned by John Kenyon, and now owned by various persons, consisting of approximately one acre, more or less, bounded on the North by land of Mary Fallon, on the East by land of John B. Kenyon, on the South by land of Frederick A. Anderson, and on the West by land of Ebba C. Anderson.
The property is further described as Lot No. 12 in Plat Book 38, Page 207, of the Land Evidence Records of the Town of Charlestown, R. I.
The terms of sale are cash in hand.
WILLIAM D. CROSS
Collector of Taxes, Town of Charlestown, R. I.
December 14, 1961
Legal Advertising 10
TOWN OF CHARLESTOWN, R.I.
Tax Collector's Sale
In Charlestown, Town Hall, notice is hereby given that by virtue of a request made by the Collector of Taxes of the Town of Charlestown, R. I. to the said Town, and in accordance with the laws of the State of Rhode Island, the following described real estate situated in the Town of Charlestown, R. I., will be sold at public auction to the highest bidder on the 14th day of February, A. D. 1962, at 10 o'clock a.m., at the Town Hall, Charlestown, R. I., or at some other convenient place known to the parties interested, for the payment of taxes due and unpaid upon the same, together with interest, costs, and charges incidental thereto, and for the payment of the request money for the sale of the premises, provided that if the tax collector shall have received the amount of all taxes due and unpaid upon the premises before the time of sale, he shall cancel the sale.
The real estate to be sold is the following:
A certain plot of land located in the Town of Charlestown, R. I., being part of a larger tract of land formerly owned by John Kenyon, and now owned by various persons, consisting of approximately one acre, more or less, bounded on the North by land of Mary Fallon, on the East by land of John B. Kenyon, on the South by land of Frederick A. Anderson, and on the West by land of Ebba C. Anderson.
The property is further described as Lot No. 12 in Plat Book 38, Page 207, of the Land Evidence Records of the Town of Charlestown, R. I.
The terms of sale are cash in hand.
WILLIAM D. CROSS
Collector of Taxes, Town of Charlestown, R. I.
December 14, 1961
Legal Advertising 10
TOWN OF CHARLESTOWN, R.I.
Tax Collector's Sale
Notice is hereby given that by virtue of a request made by the Collector of Taxes for the Town of Charlestown, R. I. to the said Town, and in accordance with the laws of the State of Rhode Island, the following described real estate situated in the Town of Charlestown, R. I., will be sold at public auction to the highest bidder at the Town Hall, Charlestown, R. I., or at some other convenient place known to the parties interested, on Tuesday, December 4, A. D. 1961, at 10 o'clock a. m., for the payment of taxes due and unpaid upon the same, together with interest, costs, and charges incidental thereto, and for the payment of the request money for the sale of the premises, provided that if the tax collector shall have received the amount of all taxes due and unpaid upon the premises before the time of sale, he shall cancel the sale.
The real estate to be sold is the following:
Certain plots of land located in the Town of Charlestown, R. I., as follows:
Lot 1, Plat 1, amount due $12.00
Lot 2, Plat 1, amount due $14.00
Lot 3, Plat 1, amount due $11.00
Lot 4, Plat 1, amount due $13.00
Lot 5, Plat 1, amount due $15.00
Lot 6, Plat 1, amount due $12.00
Lot 7, Plat 1, amount due $16.00
Lot 8, Plat 1, amount due $14.00
Lot 9, Plat 1, amount due $13.00
Lot 10, Plat 1, amount due $15.00
Lot 11, Plat 1, amount due $12.00
Lot 12, Plat 1, amount due $16.00
Lot 13, Plat 1, amount due $14.00
Lot 14, Plat 1, amount due $13.00
Lot 15, Plat 1, amount due $15.00
Lot 16, Plat 1, amount due $12.00
Lot 17, Plat 1, amount due $16.00
Lot 18, Plat 1, amount due $14.00
Lot 19, Plat 1, amount due $13.00
Lot 20, Plat 1, amount due $15.00
Lot 21, Plat 1, amount due $12.00
Lot 22, Plat 1, amount due $16.00
Lot 23, Plat 1, amount due $14.00
Lot
The page as recorded