The instrument's own words
page 1 · read by Gemma vision
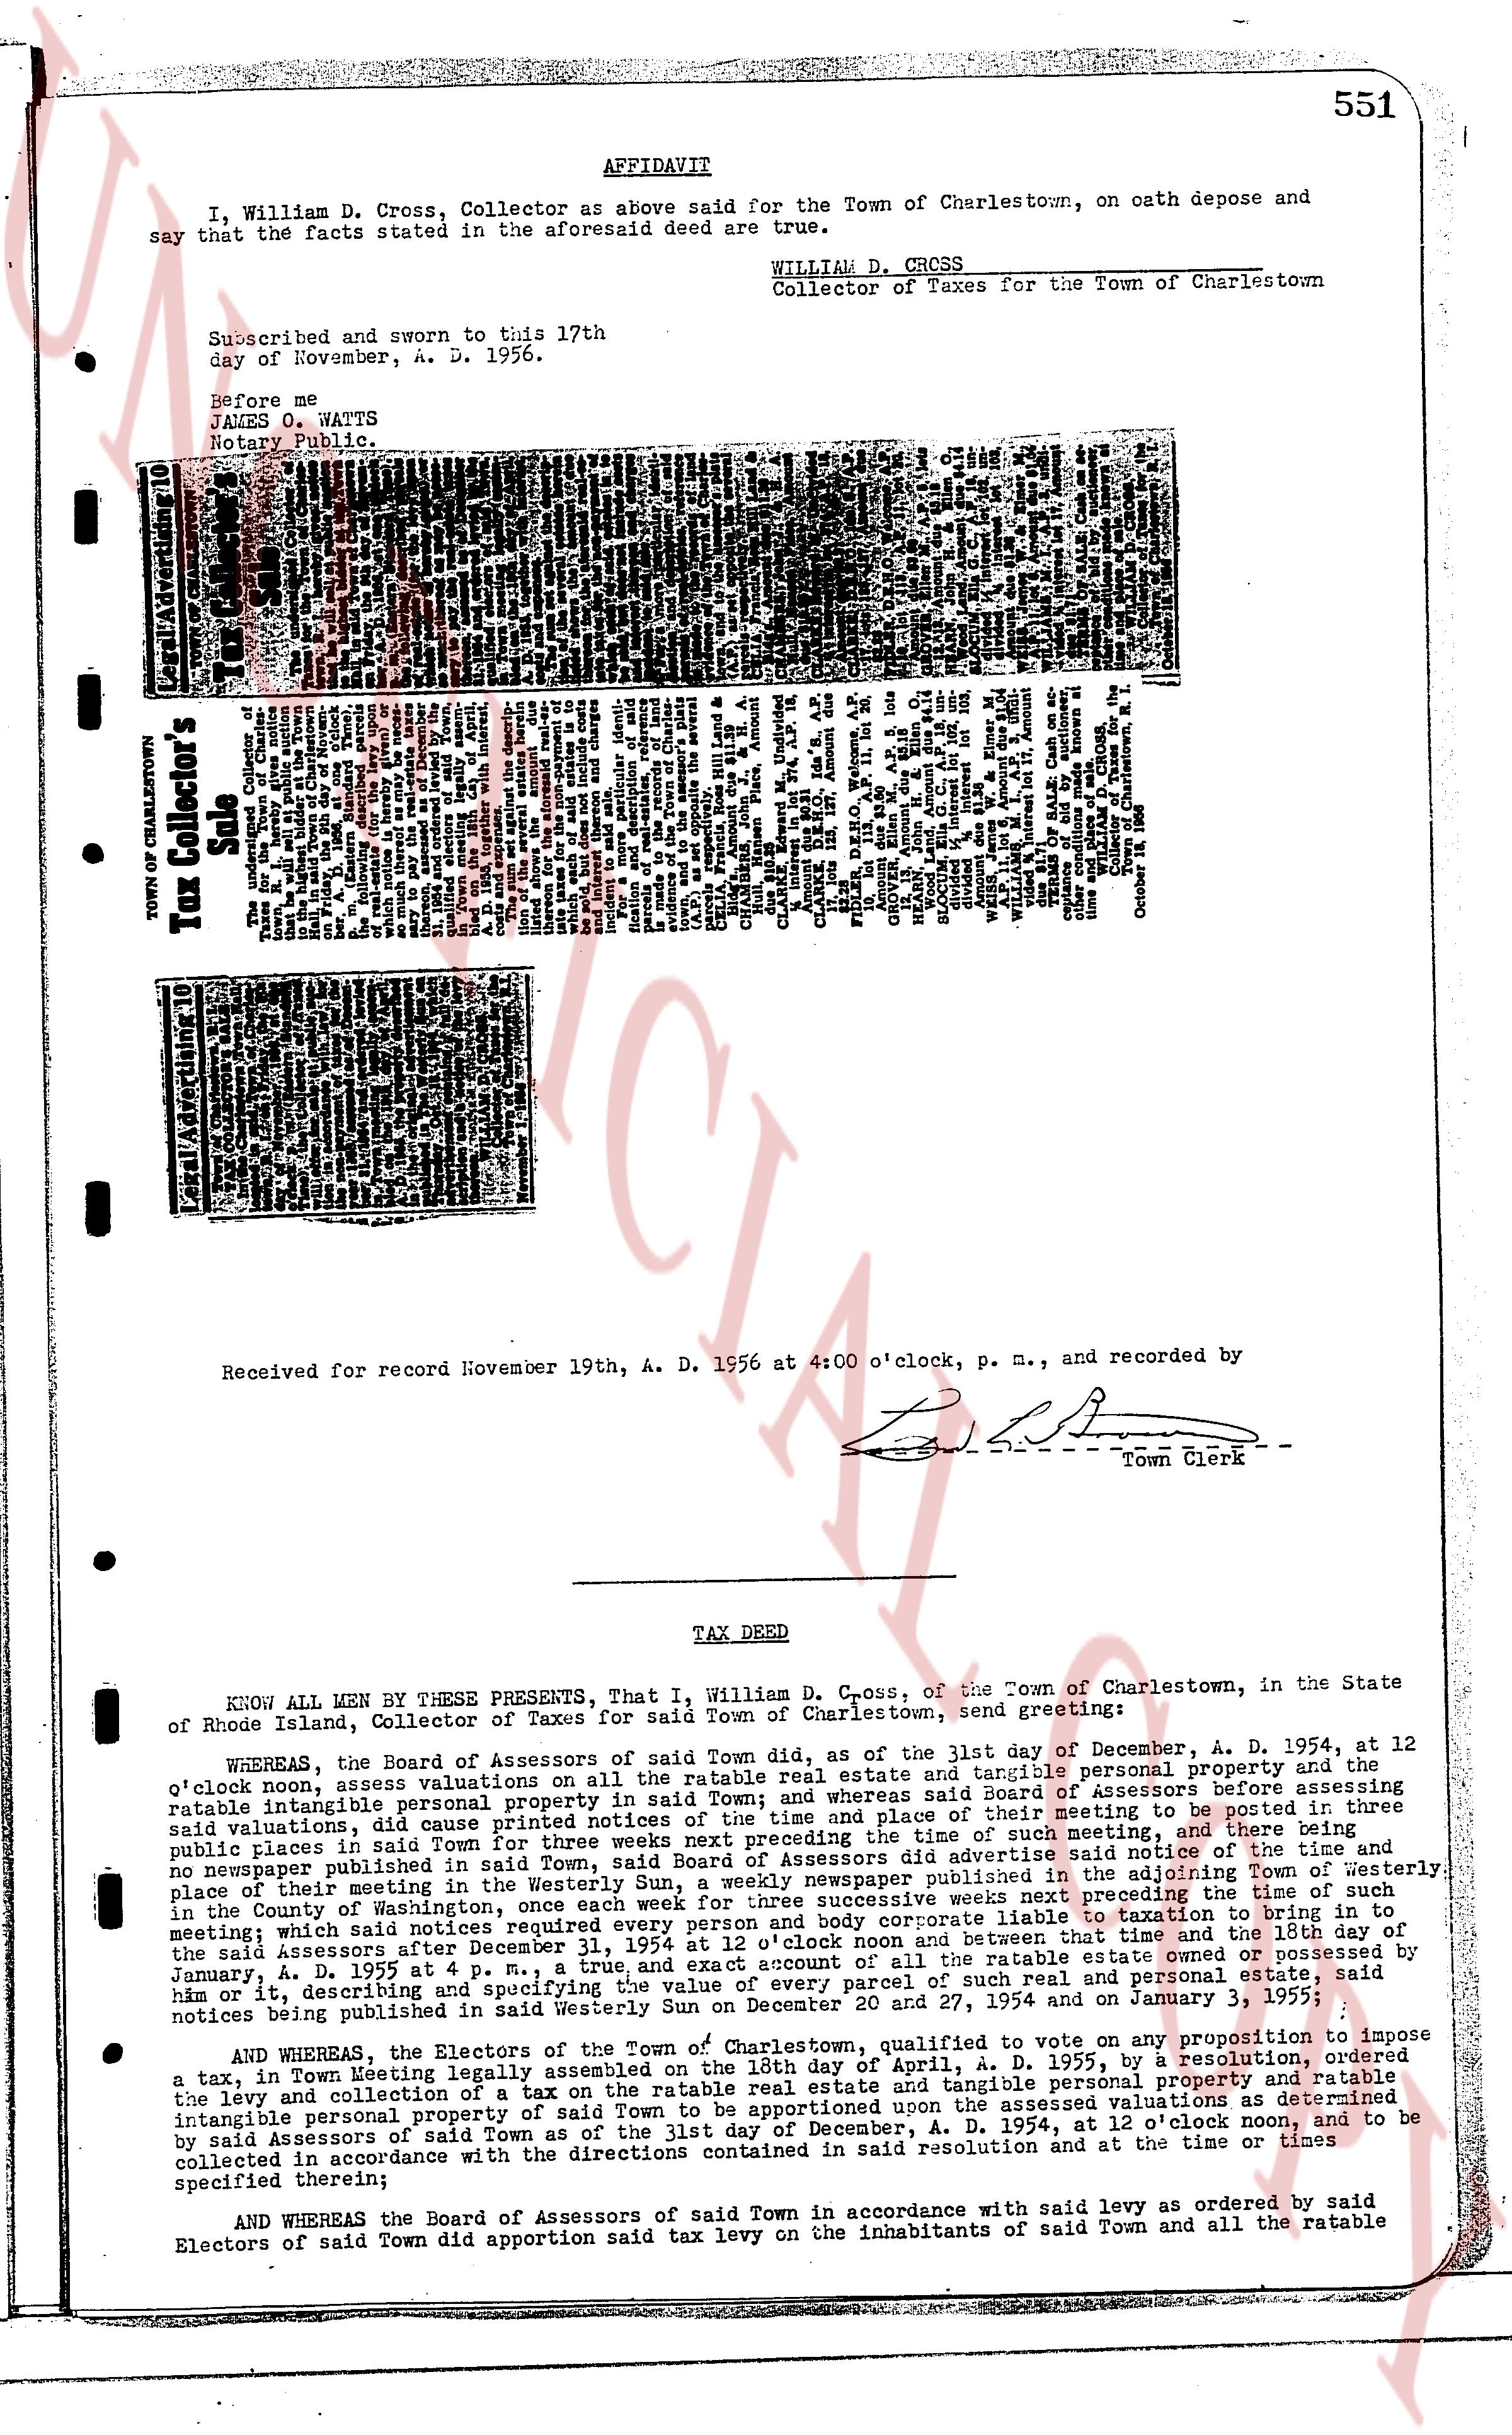
551
AFFIDAVIT
I, William D. Cross, Collector as above said for the Town of Charlestown, on oath depose and say that the facts stated in the aforesaid deed are true.
WILLIAM D. CROSS
Collector of Taxes for the Town of Charlestown
Subscribed and sworn to this 17th
day of November, A. D. 1956.
Before me
John D. WATTS
Notary Public.
----
TOWN OF CHARLESTOWN
Tax Collector's
Sale
Legal Advertising:
The Town of Charlestown, Rhode Island,
by its Collector of Taxes, will sell at public
auction, to the highest bidder, for cash, the
following described real estate, together with
the buildings thereon, if any, and the rights
thereunto belonging, for the payment of taxes
due to the Town of Charlestown, Rhode Island,
and the costs of this sale.
The property to be sold is as follows:
Lot 10, Plat 1, Charlestown, Rhode Island,
being the land and buildings owned by
Samuel J. Miceli and Irene E. Miceli,
and more particularly described in a deed
recorded in Book 35, Page 551, of the
land evidence records of the Town of
Charlestown, Rhode Island.
The sale will be held at the Town Hall,
Charlestown, Rhode Island, on the 17th day
of November, 1956, at 10 o'clock in the
forenoon, and will continue until the property
is sold.
The Collector of Taxes will sell the
property to the highest bidder for cash.
The purchaser will be required to pay
the full amount of the purchase price
at the time of the sale.
The legal advertising for this sale was
published in the Charlestown Times, a
newspaper of general circulation in the
Town of Charlestown, Rhode Island, on
the 3rd, 10th, and 17th days of November,
1956.
The Town of Charlestown, Rhode Island,
makes no warranty as to the title of the
property to be sold. The purchaser will
take the property subject to all easements,
restrictions, and encumbrances of record.
The Town of Charlestown, Rhode Island,
reserves the right to cancel the sale at
any time prior to the sale.
Dated this 17th day of November, 1956.
WILLIAM D. CROSS
Collector of Taxes
Town of Charlestown, Rhode Island
----
Received for record November 19th, A. D. 1956 at 4:00 o'clock, p. m., and recorded by
[Signature]
Town Clerk
TAX DEED
KNOW ALL MEN BY THESE PRESENTS, That I, William D. Cross, of the Town of Charlestown, in the State of Rhode Island, Collector of Taxes for said Town of Charlestown, send greeting:
WHEREAS, the Board of Assessors of said Town of Charlestown, as of the last day of December, A. D. 1954, at 12 o'clock noon, made valuations on all taxable real, mixed and personal estates and all taxable personal property and the taxable tangible personal property in said Town; and whereas said Board of Assessors before assessing said valuations, did cause printed lists of the names of the owners of said estates and the amount of said valuations, due payment of which were three weeks next preceding the time of such meeting, and there being no newspaper published in said Town, said Board of Assessors did cause said lists to be posted in three public places in said Town, and also did cause the same to be published weekly newspaper published in the adjoining Town of Westerly, in the County of Washington, once each week for three successive weeks immediately following the time of such meeting; and whereas said Board of Assessors did cause a notice to be given to all persons whom it may concern, that they may appear before said Board of Assessors on December 31, 1955 at 12 o'clock noon and return to them a correct statement of the real, mixed and personal estate owned or possessed by them as of January 1, 1955 and a correct statement of the taxable tangible personal property owned or possessed by them as of December 31, 1954 or by describing and specifying the value of every parcel of such real and personal estate and of every piece of taxable tangible personal property owned or possessed by them, on or before January 1, 1955) notices being published as aforesaid;
AND WHEREAS, the Legislative Body of the Town of Charlestown, voted on any proposition to impose and levy a tax, at their Meeting legally assembled on the 18th day of April, A. D. 1955, by a resolution, ordered the levy and collection of a tax on the taxable real, mixed and personal estates and all taxable personal property in said Town to be apportioned upon the assessed valuations as determined by said Board of Assessors of said Town as of the last day of December, A. D. 1954, and such tax to be collected in accordance with the directions contained in said resolution and at the time or times specified therein;
AND WHEREAS the Board of Assessors of said Town in accordance with said levy as ordered by said Electors of said Town did apportion said tax levy on the inhabitants of said Town and all the ratable
page 2 · read by Gemma vision
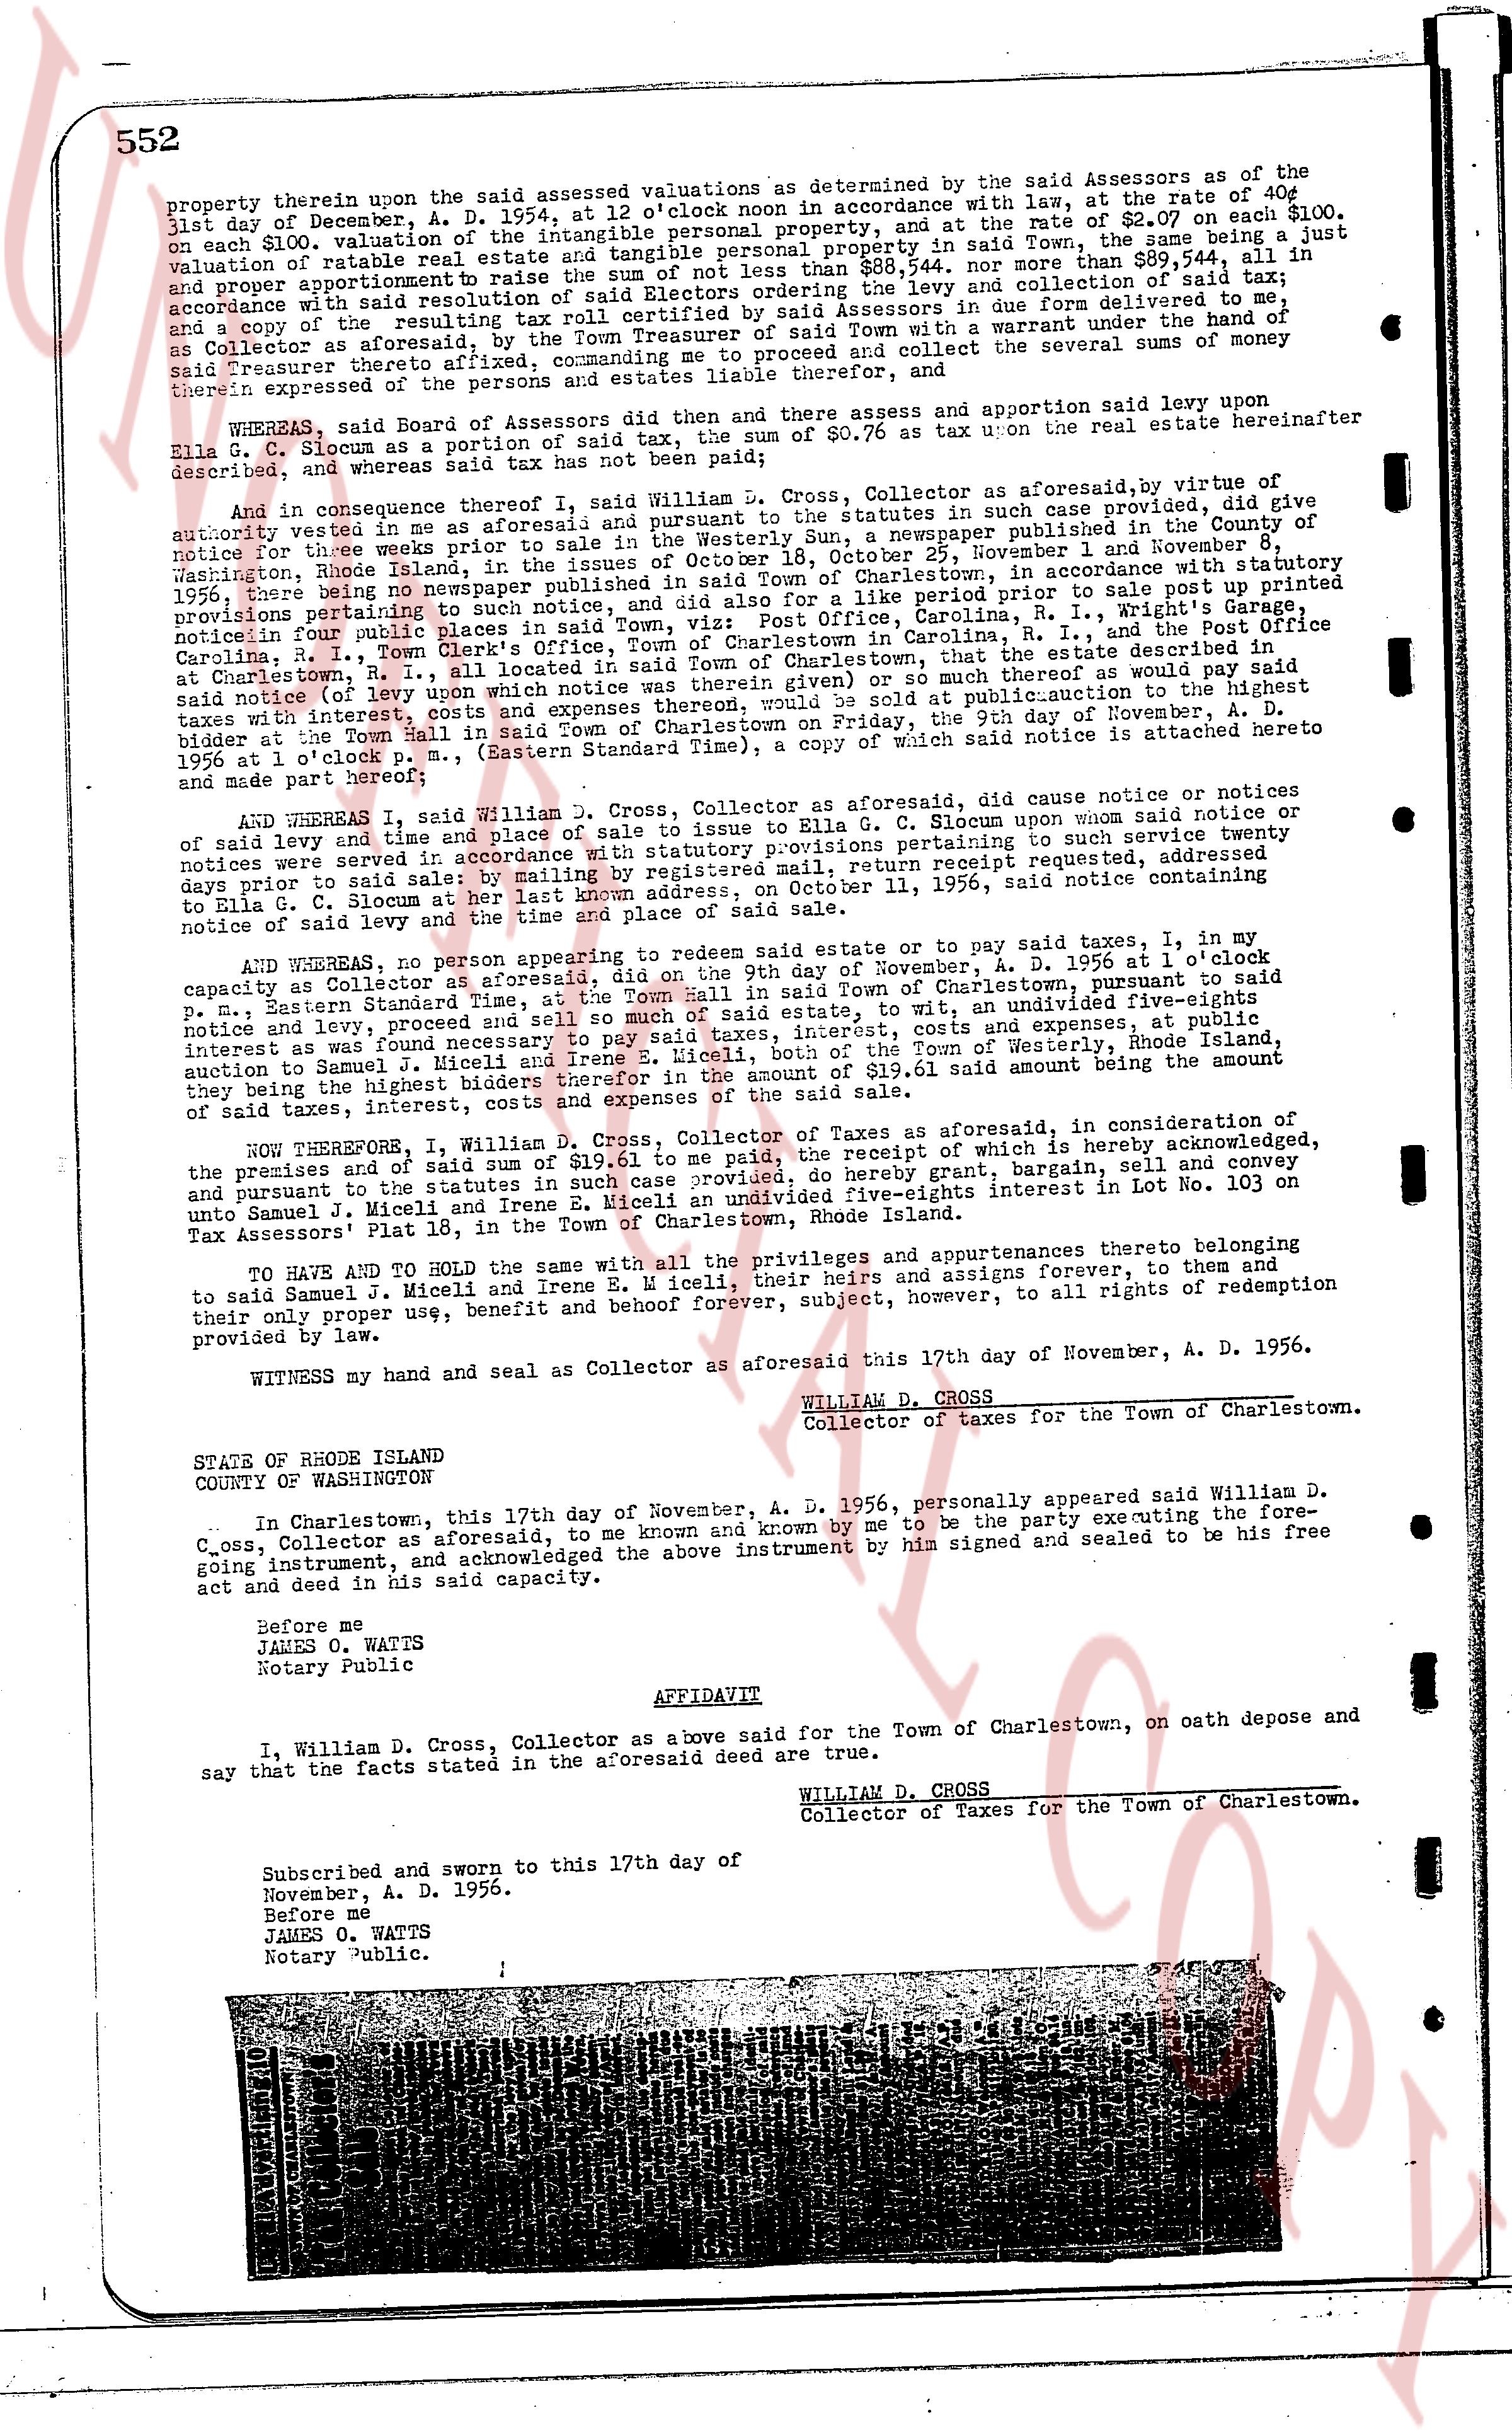
552
property therein upon the said assessed valuations as determined by the said Assessors as of the August 1st day of December, A. D. 1954, at 10% discount and accordance with law, at the rate of 40% on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10% on taxable personal property, and at the rate of $2.07 on each $100, on each $100, stvarnity of real estate and 10%
page 3 · read by Gemma vision
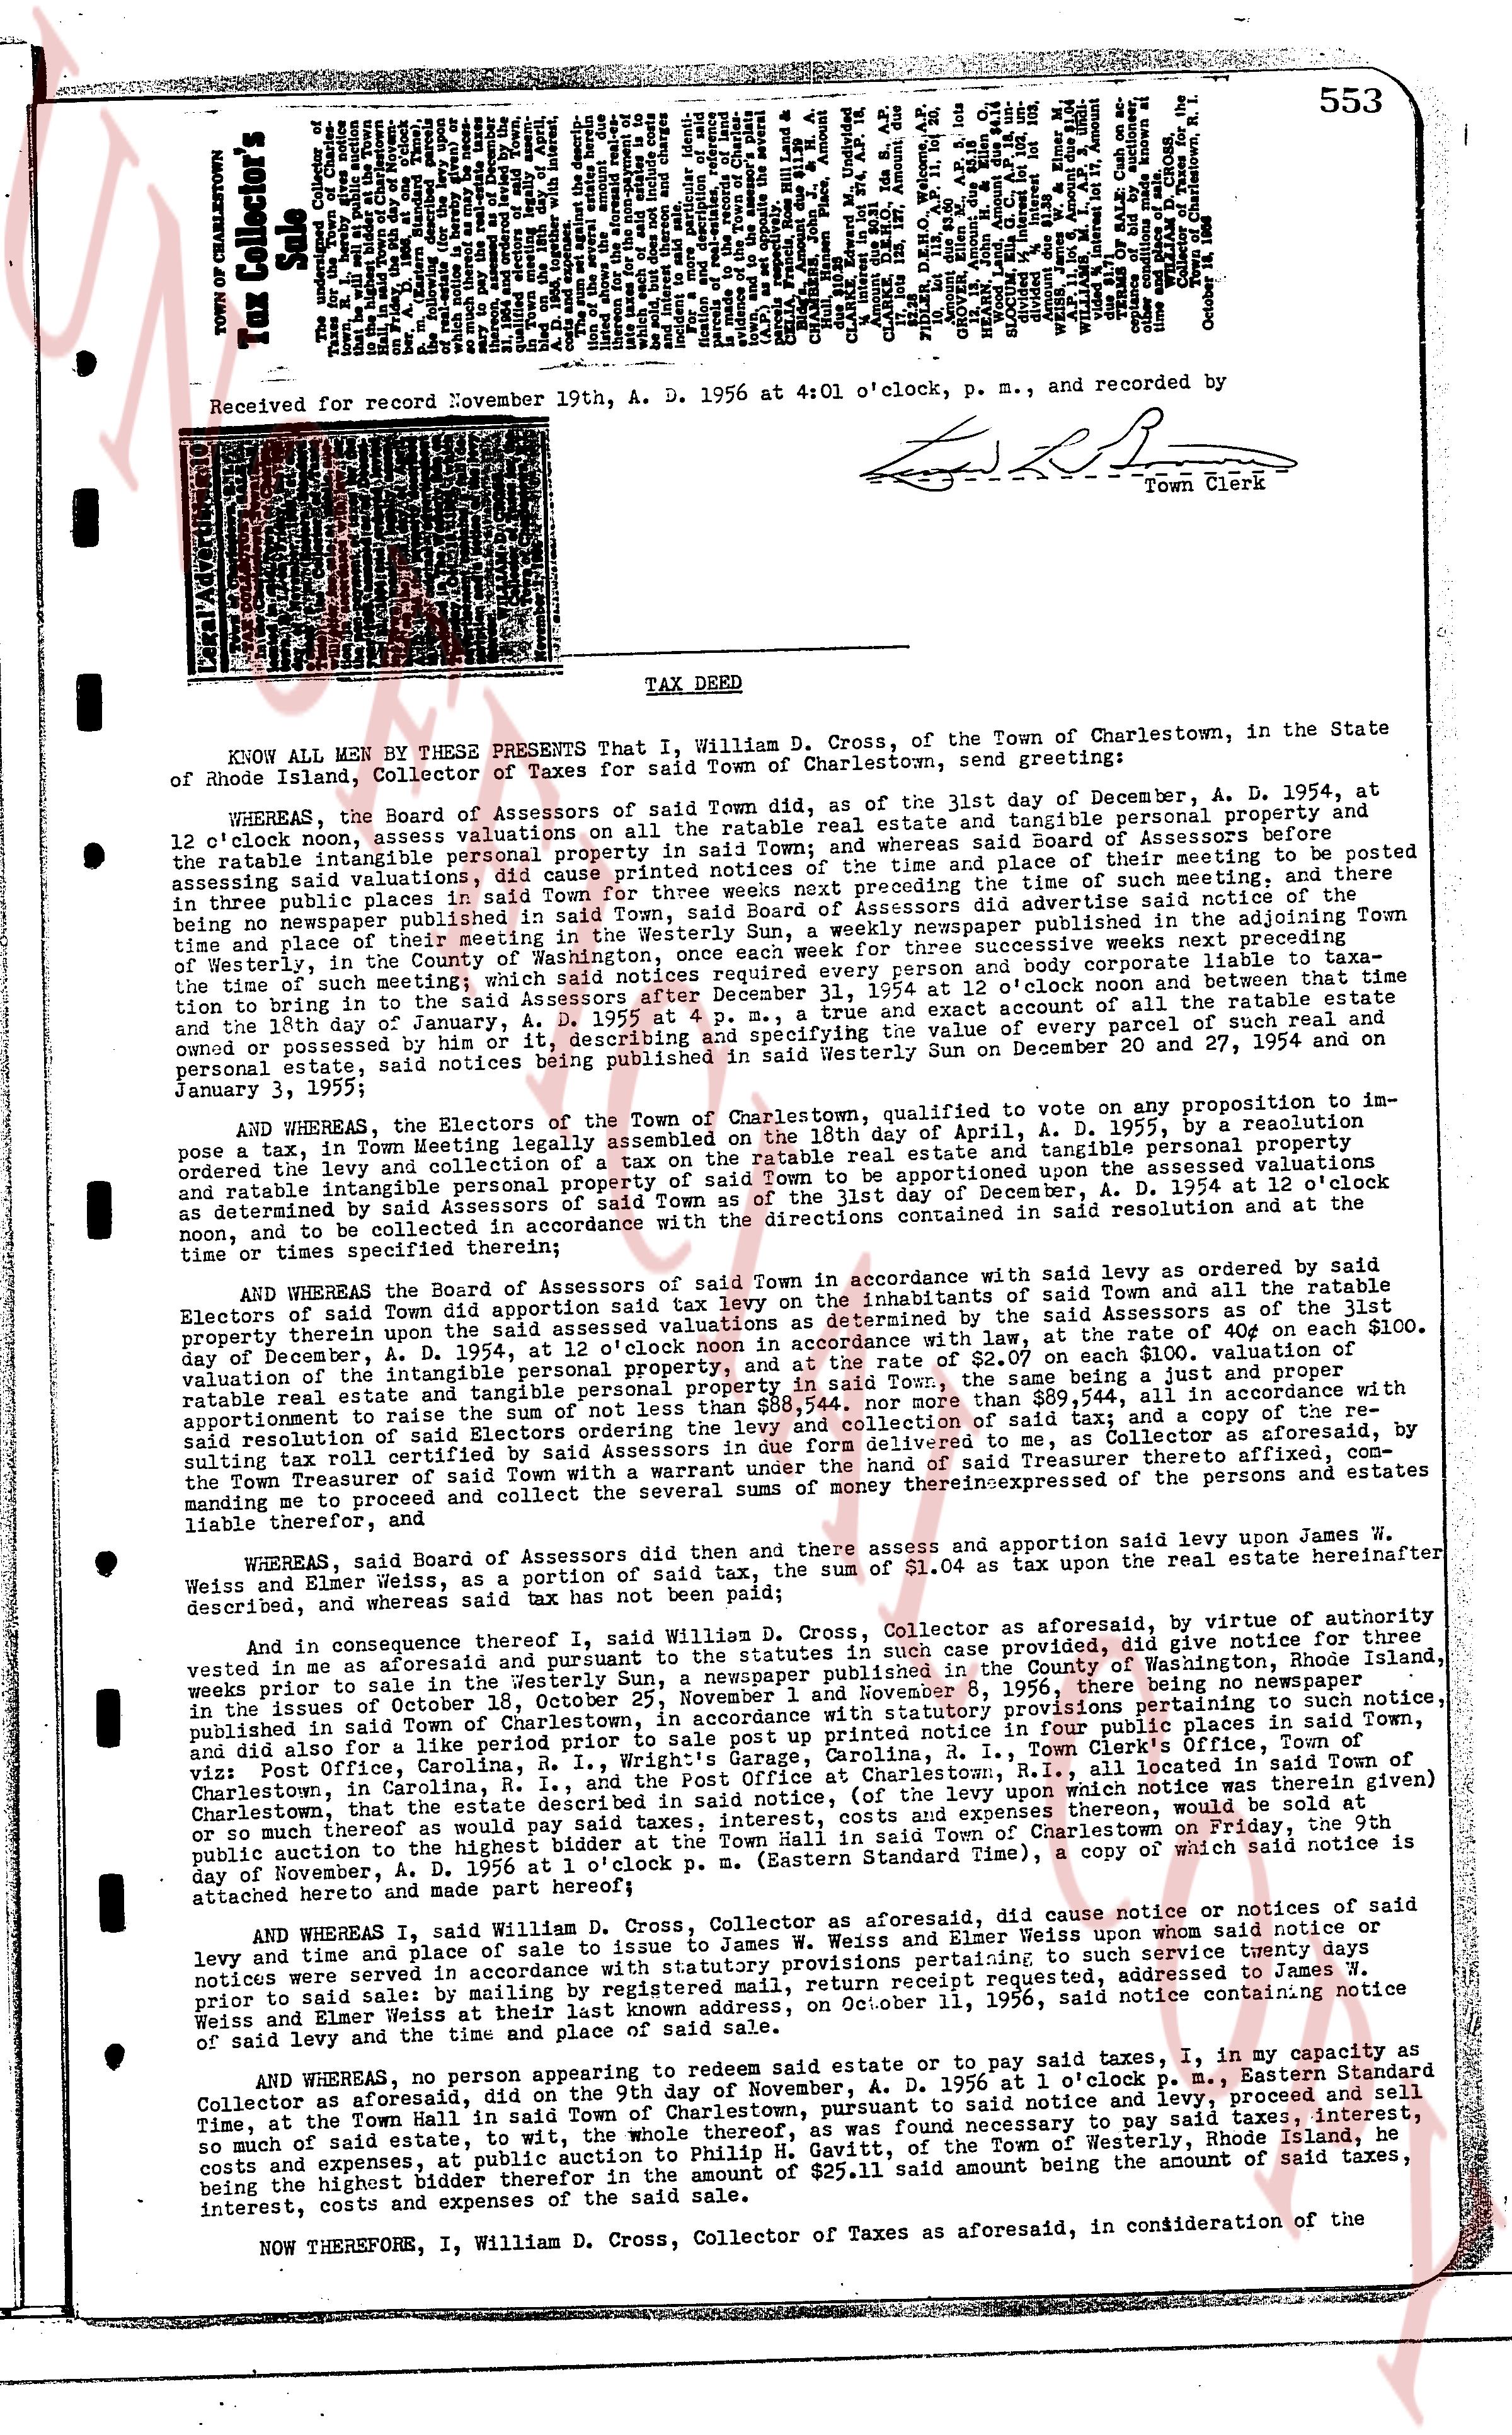
553
TOWN OF CHARLESTOWN
Tax Collector's
Sale
The Town of Charlestown, Rhode Island,
by its Tax Collector, William D. Cross,
to Samuel J. Miceli and Irene E. Miceli,
of Westerly, Rhode Island,
for the sum of $25,11.00,
and in consideration of the payment of
taxes, interest, and costs,
does hereby grant, bargain, sell and
convey, with warranty,
all that certain lot of land,
situated in the Town of Charlestown,
and known as Lot 1,
on the Plat of the estate of
Ella G. C. Slocum,
as the same appears on the plat
recorded in the land evidence records
of the Town of Charlestown,
and more particularly described as follows:
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
[?]
The page as recorded