The instrument's own words
page 1 · read by Gemma vision
207
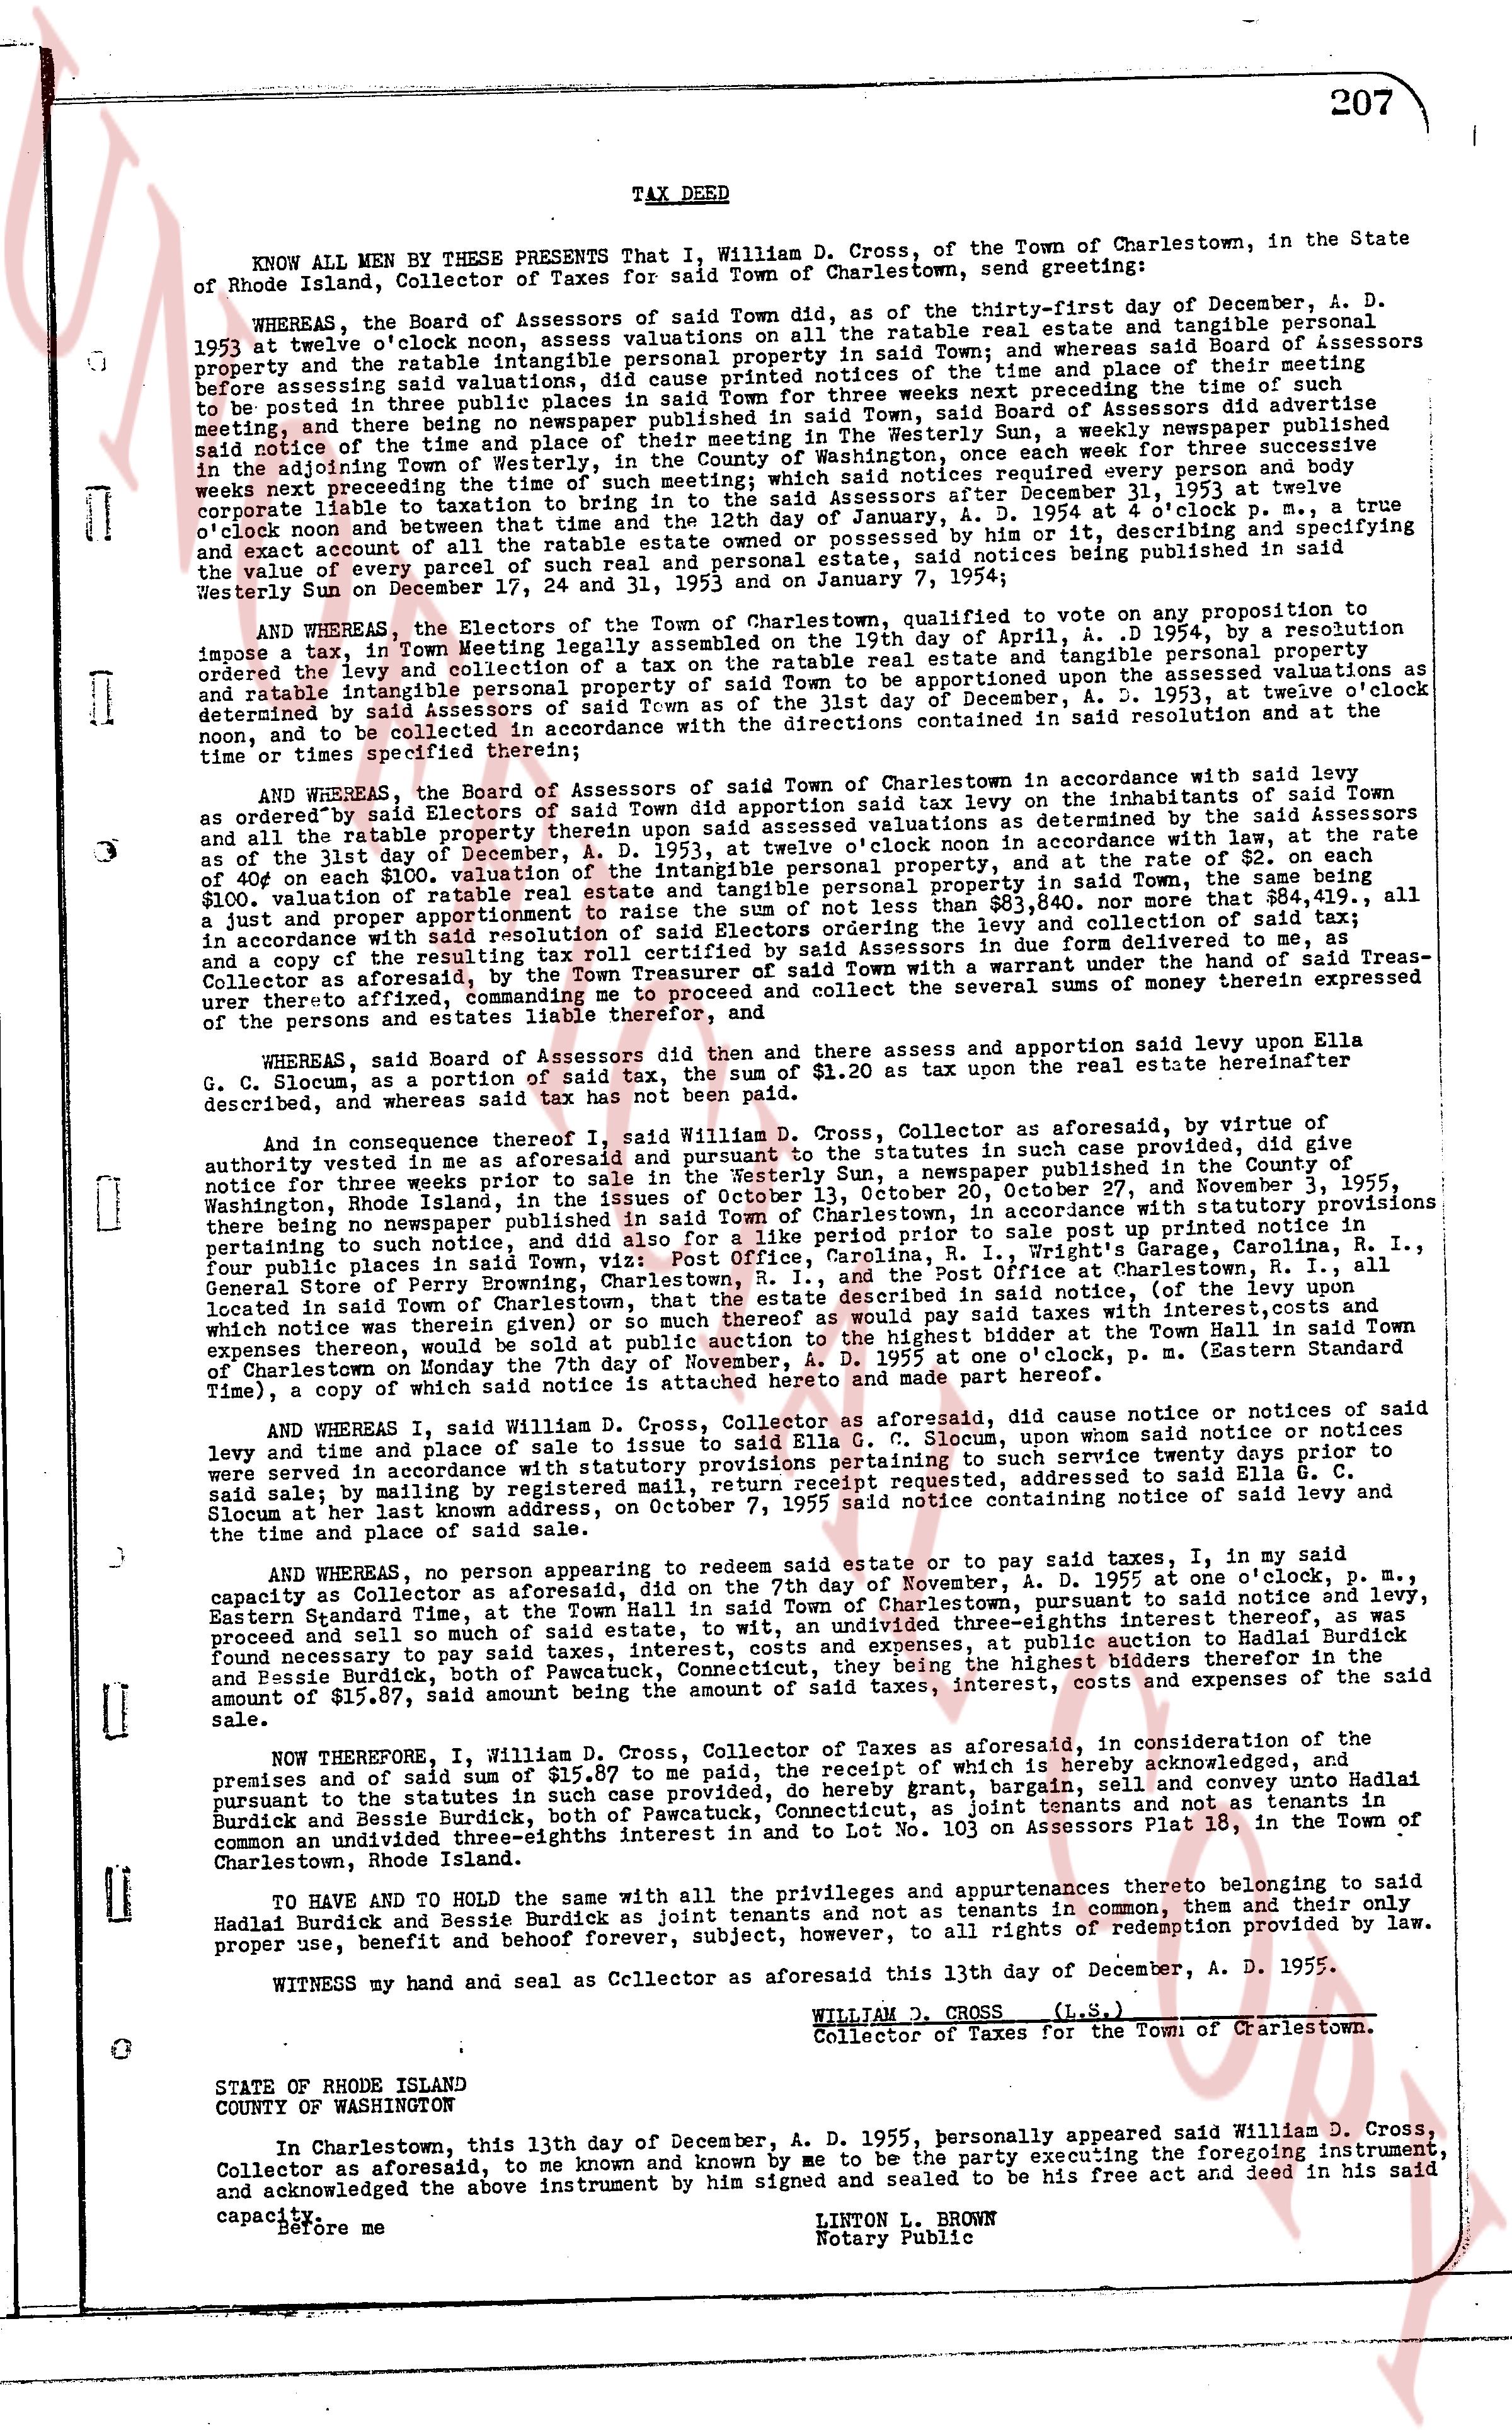
TAX DEED
KNOW ALL MEN BY THESE PRESENTS That I, William D. Cross, of the Town of Charlestown, in the State of Rhode Island, Collector of Taxes for said Town of Charlestown, send greeting:
WHEREAS, the Board of Assessors of said Town did, as of the thirty-first day of December, A. D. 1953, at twelve o'clock noon, make and set valuations on all the ratable real estate and tangible personal property in said village and town, and in accordance with the statutory provisions relating to the appointment of Assessors property and the ratable tangible estate informed the Board of Assessors of the notices of the time and place of their meeting being set and published as follows: that the notice of the time and place for three weeks preceding the meeting to be posted in three public places in said Town for three weeks preceding the meeting; said Board of Assessors did advertise said notice of the time and place of their meeting in the Westerly Sun, a weekly newspaper published in the Town of Westerly, County of Washington, State of Rhode Island, for three successive weeks immediately preceding the time of such meeting; which said notices required every person whose corporate liability to the tax was concerned to deliver to said Board of Assessors on or before 12 o'clock p.m. at twelve o'clock p.m. and between that time and the 12th day of January, A. D. 1954 at 4 o'clock p.m., a true and exact account of all such real estate and tangible personal property as he or she owned, and a certifying the value of the same part of such real estate and personal estate, said notices being published in said Westerly Sun on December 17, 24 and 31, 1953 and on January 7, 1954.
AND WHEREAS, the Electors of the Town of Charlestown, in convention, qualified to vote on appropriation by resolution in said Town Meeting held in said Town and approved on the 19th day of April, 1954, a resolution imposed the levy and collection of a tax on the ratable real estate and tangible personal property as determined ordered the levy and collection of a tax on the ratable real estate and tangible personal property as determined by the Board of Assessors of said Town, and that said tax should be apportioned upon the assessed valuations as determined by said assessors of said Town as of the last day of December, A. D. 1953, and that the rate of tax should be determined by said assessors of said Town as of the last day of December, A. D. 1953, and that said rate of tax was determined in said resolution and at the time so determined specified as therein:
AND WHEREAS, the Board of Assessors of said Town of Charlestown in accordance with said levy said law and according to the laws of said Town did apportion said tax levy on the inhabitants of said Town as follows: on the ratable real estate and tangible personal property as determined by said assessors in accordance with the law, at the rate of, on the ratable real estate, at the rate of, on the $100 valuation of the intangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each $100 valuation of ratable real estate, at the rate of, on each $100 valuation of tangible personal property, and at the rate of, on each
page 2 · read by Gemma vision
208
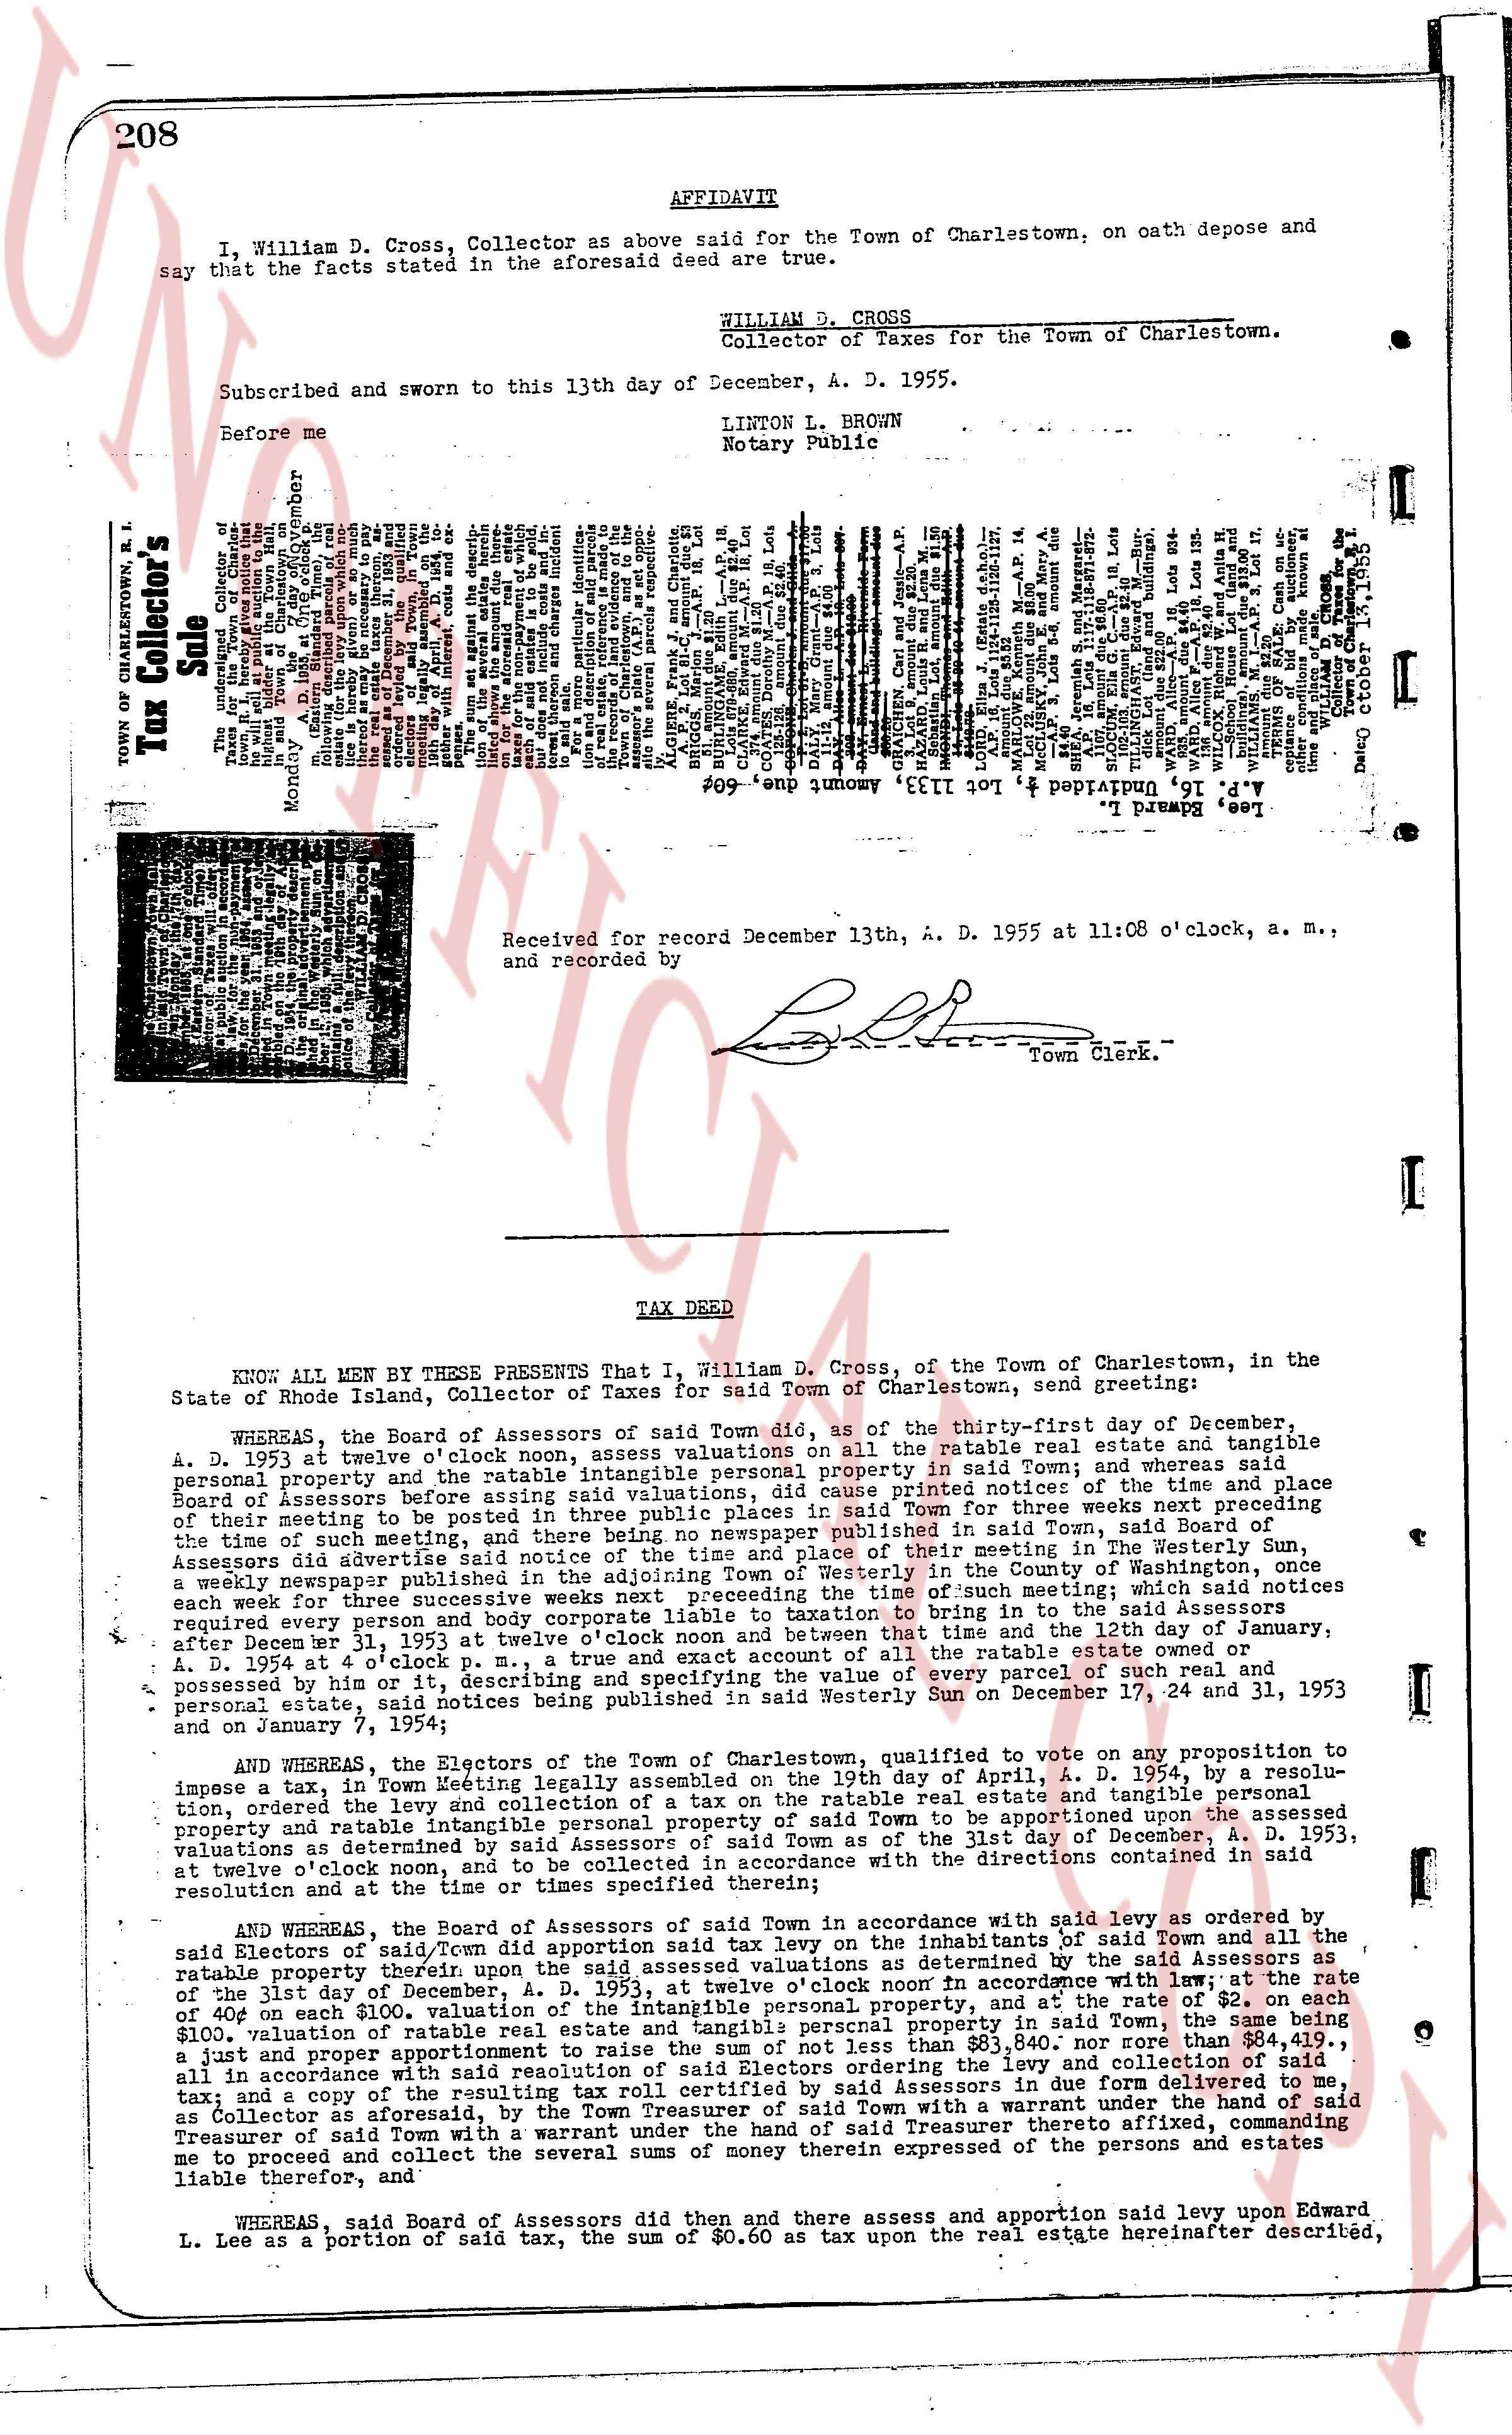
AFFIDAVIT
I, William D. Cross, Collector as above said for the Town of Charlestown, on oath depose and say that the facts stated in the aforesaid deed are true.
WILLIAM D. CROSS
Collector of Taxes for the Town of Charlestown.
Subscribed and sworn to this 13th day of December, A. D. 1955.
Before me
LINTON L. BROWN
Notary Public
Town of Charlestown, R. I.
Tax Collector's
Book
The Collector of Taxes for the Town of Charlestown, R. I. hereby certifies that the taxes on the real estate and tangible personal property described in the attached deed have been paid in full up to and including the tax year 1954.
The property is described as follows:
Lot 10, Plat 1, as shown on the map of the "Everett Graichen" estate, as recorded in the land evidence records of the Town of Charlestown, Rhode Island, in Book 35, Page 103.
The amount of taxes paid is as follows:
Year 1954: $ [?]
Year 1953: $ [?]
Year 1952: $ [?]
Year 1951: $ [?]
Year 1950: $ [?]
Total: $ [?]
Dated this 13th day of December, A. D. 1955.
WILLIAM D. CROSS
Collector of Taxes
[Stamp: "Filed 8/24/1955"]
----
Received for record December 13th, A. D. 1955 at 11:08 o'clock, a. m., and recorded by
[Signature]
Town Clerk.
----
TAX DEED
KNOW ALL MEN BY THESE PRESENTS That I, William D. Cross, of the Town of Charlestown, in the State of Rhode Island, Collector of Taxes for said Town of Charlestown, send greeting:
WHEREAS, the Board of Assessors of said Town did, as of the thirty-first day of December, A. D. 1953 at twelve o'clock noon, assess valuations on all the ratable real estate and tangible personal property and the ratable income of inhabitants of said Town and residents within said Town and non-residents before assessing said valuations, did cause printed notices of the time and place of their meeting to be posted in three public places within said Town and cause the said Board of Assessors to give notice of their meeting to be posted in three public places within said Town and cause a notice of their meeting to be published in a newspaper published in said Town, said Board of Assessors did advertise said notice of the time and place of their meeting to be posted in three public places within said Town and cause a notice of their meeting to be published in a newspaper published in the County of Washington, once each week for three successive weeks next preceding the time of such meeting; and further did give notices required by law to the persons interested in said valuations by mailing or delivering to said Assessors after December 31, 1953 at twelve o'clock noon and between that time and the 12th day of January, 1954, a notice of the ratable value of the real estate and tangible personal property and ratable income possessed by him or others, describing and specifying the value of every parcel of such real and personal property, said notices being published in said Town and in a newspaper published in said Town, 1953 and on January 7, 1954;
AND WHEREAS, the Electors of the Town of Charlestown, being qualified to vote on any proposition to impose a tax, in Town Meeting legally assembled on the 12th day of April, A. D. 1954, by a resolution, did vote for the levy and collection of a tax on the ratable real estate and tangible personal property and ratable income of inhabitants of said Town and residents within said Town and non-residents property and ratable intangible personal property of said Town Assessors as of the first day of December, A. D. 1953, valuations at twelve o'clock noon, and to collect in accordance with the directions contained in said resolution, said resolution being as follows:
"Resolved, That the Town of Charlestown levy a tax at the rate of $1.00 on every $100.00 of valuation of ratable real estate and tangible personal property in said Town, the same being a just and proper assessment of the taxable property in said Town, and that said tax be collected in accordance with said resolution of said Electors ordering the levy and collection of said tax and a copy of the resulting tax roll be filed with the Town Clerk and in our further resolution that the Collector of Taxes for the Town Treasurer of said Town Treasurer of said Town Treasurer there be authorized to levy and collect the several sums of money therein expressed of the persons and estates liable therefore, and
WHEREAS, said Board of Assessors did then and there assess and apportion said levy upon Edward L. Lee as a portion of said tax, the sum of $0.60 as tax upon the real estate hereinafter described,
The page as recorded